Motor carrier classes by state

Kentucky hot shot trucking insurance for light-combination and expedited freight operators

Kentucky puts two lines in very different places. The safety rules arrive where the federal definition puts them. The certificate and the filed insurance policy arrive at the first paid load, at any weight, with no lower bound written anywhere in the chapter — and the gap between the two is ten thousand pounds wide.

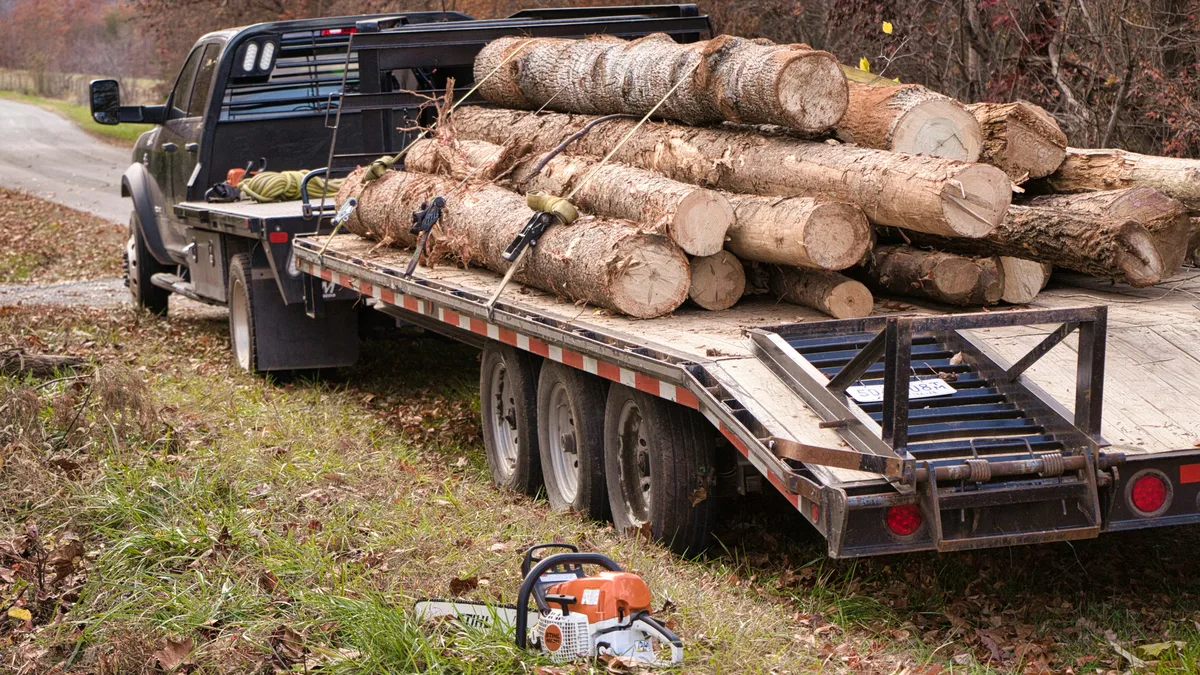
Flatbed dually towing a gooseneck flatbed trailer loaded with logs — Kentucky Hot Shot Trucking Insurance from Truck Guard Insurance

Much of what makes this work difficult has nothing to do with the Commonwealth — it is the trade behaving as it behaves anywhere there are roads. Rather than repeat it, that ground is held by the hot shot trucking insurance page instead of here.

What Kentucky adds is a gap. On the safety side the state imports the federal definition without altering it: 601 KAR 1:005 Section 2 governs “[a] commercial motor vehicle and its operator meeting the definitions established in 49 C.F.R. 390.5 operating for-hire or in private carriage, interstate, or intrastate”. The line that produces is the federal one, and Kentucky writes no number of its own there.

On the economic side there is no line at all. KRS 281.630(1) provides that “[a] person shall not act as a motor carrier without first obtaining a certificate from the department”, and KRS 281.655(1) makes a filed and approved policy a precondition of that certificate. Neither sentence contains a weight, and the definition of motor carrier they depend on does not contain one either.

So a Kentucky operation can be below every safety threshold in the state and still owe a certificate, a per-vehicle license and a filed policy on the day it takes money to move somebody else’s freight. Each number that follows is tied to the enacting document, and one number in the liability table is left open on purpose, because the enacting document leaves it open.

Hauling for compensation inside Kentucky at any weight? The certificate and the filed policy do not wait for a weight threshold, and the statute cancels the operating rights the moment the policy does.

Send the certificate number if you hold one, the per-vehicle license count, and the registered and actual weights of the combination. The last of those decides which rung of the liability table the account argues for — and the statute does not settle the argument.

Start a Kentucky quote

The duty attaches to acting as a carrier, not to owning a particular truck

The operative sentence is nine words long before it names anything. KRS 281.630(1): “A person shall not act as a motor carrier without first obtaining a certificate from the department.” Subsection (2) confirms that the property side is inside it: “[a] certificate for the intrastate transportation of passengers or property, including household goods, shall be issued to any qualified applicant authorizing operation covered by the application, if it is found that the applicant conforms to the provisions of this chapter and the requirements of the administrative regulations promulgated in accordance with this section.”

The class term carries no equipment description. KRS 281.010(34) defines a motor carrier as “any person in either a private or for-hire capacity who owns, controls, operates, manages, or leases, except persons leasing to authorized motor carriers, any motor vehicle for the transportation of passengers or property upon any highway, and any person who engages in the business of automobile utility trailer lessor, vehicle towing, driveaway, or U-Drive-It”.

Read that definition against the truck in the yard and nothing in it asks how much the truck weighs. It asks what the person does. A one-truck operation that books a load, moves it and invoices for it is inside the sentence, and there is no lower boundary written under it.

There is a phrase in the definition worth pausing on because it is the whole difference between two kinds of account. “[E]xcept persons leasing to authorized motor carriers” removes the operator who is leased on to somebody else’s authority from the definition in that capacity. That operator is inside the lessee carrier’s certificate for the dispatched movement, and outside everything the rest of the time — which is a coverage question rather than a licensing one, and the reason non-trucking liability is a live line on a Kentucky submission.

Sixteen exemptions, read in full, and none of them is a weight

The economic chapter has an exemption section and it opens with a carve-back that has to travel with any quotation from it. KRS 281.605 begins: “The provisions of this chapter shall not apply, except as to safety regulations, to:” — and then runs to sixteen numbered subsections.

Those four words in the middle change the meaning of everything after them. An operator who falls inside one of the sixteen is out of the economic chapter and still inside the safety regime. Exemption from Chapter 281 is never exemption from 601 KAR 1:005, because the section says so in its own lead-in.

All sixteen subsections were read for this page and none of them is weight-based. The list covers school buses in the transportation of students; vehicles used exclusively for named agricultural, dairy and forest products while owned by the producer; and a further fourteen categories of the same shape. The closest thing to a general-carriage exclusion is at KRS 281.605(5), which removes “[m]otor vehicles owned in whole or in part by any person and used by such person to transport commodities of which such person is the bona fide owner, lessee, consignee, or bailee; provided, however, that such transportation is for the purpose of sale, lease, rent, or bailment, and is an incidental adjunct to an established private business … other than the business of transportation of property for hire”.

That last clause is the one that matters. Hauling one’s own goods as an adjunct to another business is outside the chapter. Hauling other people’s goods for money is the business the clause expressly excludes from the exemption. There is no reading of the sixteen that reaches a for-hire general-freight operation, at any weight.

  • The lead-in reads “shall not apply, except as to safety regulations” — the safety regime survives every exemption on the list.
  • Sixteen subsections, read in full; none is keyed to a weight.
  • The private-carriage exemption at (5) is expressly limited to business “other than the business of transportation of property for hire”.
  • There is no general-freight entry, so a for-hire light combination stays inside the chapter.

The property certificate is the cheap one, and the truck is licensed separately

Kentucky issues thirteen kinds of certificate and prices twelve of them the same. KRS 281.630(3)(a) lists them: taxicab, limousine, disabled persons vehicle, transportation network company, household goods, charter bus, bus, U-Drive-It, property, driveaway, peer-to-peer car sharing, automobile utility trailer, and towing and storage.

The fee schedule at KRS 281.630(3)(b) then singles out one: “[t]he department shall receive an application fee of two hundred fifty dollars ($250) for all applications, except that the department shall receive an application fee of twenty-five dollars ($25) for a property certificate.” Property carriage is the outlier, at a tenth of everything else.

The certificate is not the only credential, though, and this is where a first-time applicant most often gets the sequence wrong. KRS 281.630(3)(c)2. requires the applicant, before a certificate may issue, to “file a motor carrier vehicle license application for each motor carrier vehicle as required by KRS 281.631”, and adds that “[t]he applicant shall file at least one (1) motor carrier vehicle license application before being eligible for a certificate.”

So the company credential and the vehicle credential are separate instruments and the vehicle one comes first in the order of operations. A fleet that grows by one truck does not simply add it to an existing certificate; there is a per-vehicle filing behind each unit.

The insurance sits in the same list of prerequisites. KRS 281.630(3)(c)5. requires the applicant to “[f]ile with the department one (1) or more approved indemnifying bonds or insurance policies as required by KRS 281.655”. The filing is not a compliance step that follows the authority — it is one of the conditions of getting the authority.

Send the certificate number if you hold one, the vehicle count filed under KRS 281.631, and the registered and actual weights of the combination. Those settle which Kentucky obligations are live and which rung of the liability table the account has to be placed against.

Get a Kentucky quote

The liability table ladders at eighteen thousand pounds, and the statute does not say which weight

Kentucky is unusual in laddering its property liability minimums by weight at all. KRS 281.655(4) provides that “[t]he types and minimum amounts of insurance to be carried on each vehicle shall be as follows”, and the property table that follows — headed “MOTOR VEHICLES FOR THE TRANSPORTATION OF PROPERTY, INCLUDING U-DRIVE-ITS AND AUTOMOBILE UTILITY TRAILERS” — has exactly two rungs.

At “18,000 lbs. or less” the columns read $100,000.00 for death of or injury to any one person, $300,000.00 total liability for death of or injury to persons, and $50,000.00 property damage. At “More than 18,000 lbs.” the middle column doubles to $600,000.00 and the other two are unchanged. So the break moves one figure and leaves two alone.

The break sits in an awkward place for this configuration, and this page will not pretend otherwise. A Class 3 to Class 5 power unit with a loaded gooseneck straddles eighteen thousand pounds depending on how it is measured and what is on the deck. The column header says “Gross Weight”. The lead-in says “on each vehicle”. Neither phrase says combined, and no definition resolving gross vehicle weight rating against gross combination weight rating against registered weight was located in KRS 281.010.

Which rung applies to a truck-plus-gooseneck combination in Kentucky is therefore unverified, and it is recorded here as an open question rather than settled by inference. What is settled is that the question changes the amount and not the existence of the duty: both rungs are obligations, there is nothing below the lower one, and the table has no exit.

Handling it is simple even though the law is not. Put the question to the department before the first filing goes in, not after the first claim comes back — and until an answer arrives, place the account on the upper rung. Guessing high costs money that can be recovered at the next renewal. Guessing low leaves a layer nobody bought.

One policy, all the equipment: what “blanket coverage” does here

Two subsections either side of the table change how the figures are applied, and both are easy to miss. KRS 281.655(1) requires the applicant or certificate holder to “file or shall have on file with the department one (1) or more approved indemnifying bonds or insurance policies issued by some surety company or insurance carrier authorized to transact business within the Commonwealth of Kentucky”, and specifies that “[t]he term of each bond or policy shall be continuous and shall remain in full force until canceled under proper notice” with “the state insurance endorsement” attached.

Then KRS 281.655(3): “[a]ll bonds or policies shall provide blanket coverage for all equipment operated pursuant to the certificate or permit.” Read against the “on each vehicle” language in subsection (4), that is the reconciliation. The minimums are expressed per vehicle; the instrument that satisfies them must reach everything running under the certificate.

For a small fleet that is a useful protection and a trap in the same sentence. A unit added mid-term and operated under the certificate is inside the blanket by the statute’s own words. A unit operated outside the certificate is not, and the blanket does not extend to it merely because it is parked in the same yard.

The continuity requirement compounds it. A policy that is not written on a continuous basis, or that runs to a fixed expiry and is left to run out, does not satisfy a statute that asks for a term that “shall be continuous and shall remain in full force until canceled under proper notice.” That is a policy-form question as much as a limit question, and it is decided when the paper is issued rather than when the filing is made.

What happens the day the filing lapses

Most states treat a lapsed filing as a compliance failure to be remedied. Kentucky writes the consequence into the statute and it is immediate. KRS 281.655(9) provides that “[u]pon the cancellation of any bond or insurance policy required by this section, all operating rights granted by the certificate for which the bond or policy was filed, shall immediately cease, and the department may immediately require the cessation of all operations conducted under authority of the certificate, and may require the immediate surrender of all certificates, licenses, and other evidence of a right to act as a motor carrier.”

There is no grace period in that sentence and no reinstatement mechanic inside it. The operating rights cease on cancellation, and the department’s powers that follow — stopping operations, taking the paper back — are additional to that, not the thing that causes it.

The notice provision is what stands between an operator and that outcome. KRS 281.655(8) prevents any insurer or surety from being relieved of liability “until after the expiration of thirty (30) days’ notice to the department of an intention to cancel”, with an earlier cancellation permitted only where a substitute policy is already in force before those thirty days run out. The obligation to give that notice sits with the insurance company, and the notice goes to the department.

For a one-truck or three-truck operation, the practical reading is that the renewal calendar and the filing calendar are the same calendar, and that a lapse is not a paperwork problem with a fine attached — it is the authority switching off. That is worth building the renewal process around rather than discovering.

Cargo is a household-goods duty in Kentucky, and the regulations that once said more are repealed

The cargo answer here is a narrow yes that reads as a no for this operator. KRS 281.655(7) provides that “[b]efore any household goods certificate shall be issued or renewed, the applicant or certificate holder shall file or have on file with the department an approved insurance policy or bond compensating shippers or consignees for loss or damage to property belonging to shippers or consignees and coming into possession of the carrier in connection with its transportation service in the amounts required by 49 C.F.R. sec. 387.303(c) for interstate household goods motor carriers”, with “the Kentucky cargo policy endorsement” attached.

The trigger there is the certificate class, not the commodity being hauled on a given day. A household goods certificate brings the duty; a property certificate does not. The whole of KRS 281.655 was read for this page — the section runs to subsection (13), including a fully autonomous vehicle provision added effective July 15, 2024 — and cargo appears nowhere in it except at subsection (7).

What makes that negative unusually clean is what used to exist and no longer does. Two administrative regulations in the same chapter once carried insurance detail: 601 KAR 1:100, captioned Insurance, and 601 KAR 1:101, captioned Proof of liability and cargo insurance. Both are repealed. The chapter listing shows them as such, and the statute is now the only live source on this subject.

That is a C7 shape worth naming explicitly, because it is invisible from a citation. A secondary source written while 601 KAR 1:101 was in force would describe a cargo filing regime that no longer operates, and the citation in it still resolves — the regulation number still exists, the page still loads, and the header says repealed in a place a summary does not quote.

The consequence for a Kentucky general-freight account is that the state sets no cargo figure at all. The limit that ends up governing is whatever the shipper agreement requires, and a working motor truck cargo limit chosen against an average load will fail against the load that actually generates the claim.

Eighteen-year-olds, a Kentucky-suffixed number, and a waiver the state declined to allow

The safety regulation makes three changes that touch this operator directly, and all three are in Section 4 of 601 KAR 1:005, captioned Exemptions and Exceptions.

The first is the driver age. Section 4(2) provides that “[e]xcept for a transporter of hazardous materials subject to the requirements of 601 KAR 1:025, a motor vehicle operator who is operating a vehicle in intrastate commerce shall not be required to be twenty-one (21) years of age as established in 49 C.F.R. 391.11(b)(1), but shall be at least eighteen (18) years of age.” Two conditions attach: the operation must stay inside the state, and a hazardous-materials movement removes it. What the regulation permits also has no bearing on what a carrier will write — young drivers are rated against claims history, and a permission is not an acceptance.

The second is an identification duty. Section 4(4) requires a motor carrier operating exclusively in intrastate commerce to apply for an intrastate USDOT number on Form MCS-150 and to “[d]isplay the assigned intrastate motor carrier identification number and the name of the motor carrier in the same manner as required pursuant to 49 C.F.R. 390.21, except the identification number shall be preceded by the letters ‘USDOT’ and followed by the letters ‘KY.’”

That subsection carries a weight figure and it is the only one in the whole regulation, which makes it the easiest thing in Kentucky law to misread. The exception is “for a farm-to-market agricultural transportation motor vehicle with a gross vehicle weight rating of 26,000 pounds or less”. It governs who is excused from the number, for farm-to-market vehicles only. It is not a safety threshold and it is not an economic threshold, and reading it as either would put a line in Kentucky law that Kentucky did not draw.

The third is a place where Kentucky went the other way. The regulation’s own necessity statement records that it “establishes requirements related to exemptions from medical examination for private motor carriers of passengers that are more stringent than the requirements in 49 C.F.R. 391.68(c), which allows these carriers to avoid medical examination. Kentucky does not allow these medical waivers.” A state declaring on the face of its own instrument that it is more stringent than the federal text is a fact about that state, and it is the sort of thing an adoption-by-reference summary loses entirely.

The inputs a Kentucky file turns on

Premium is not published and cannot be estimated responsibly from a distance. What can be set out is the evidence a file turns on, arranged the way the Commonwealth arranges its own demands: the credential first, then the truck, then the freight.

Authority posture is the first question and in this state it is close to the only structural one. An operation holding its own property certificate owes the certificate, the per-vehicle licenses under KRS 281.631, and the filed policy in its own name, and its operating rights stop the day the policy is canceled. An operator leased to an authorized carrier is expressly outside the motor carrier definition in that capacity and inside somebody else’s filings for the dispatched movement only.

Weight matters here in a way it does not in most states, because the eighteen-thousand-pound break in KRS 281.655(4) is a real line with a real dollar consequence and the statute does not say which weight it measures. Registered weight, actual gross weight and the ratings on both units are all worth having in front of you when the account is placed, precisely because the argument for a rung has to be made from facts rather than from the text.

Geography follows. Seven states touch Kentucky. Staying inside the Commonwealth keeps both the Section 4(2) age provision and the KY-suffixed identification format available; crossing puts that trip somewhere else. Because loads on this class are taken when a truck happens to be free, what is worth having is a record of where the freight actually went, not a figure for how far it could go.

Commodity drives the cargo limit almost entirely, because the state sets none for property carriage. Light-combination freight skews to value per pound well above what the weight suggests — machine components, controlled-temperature loads, replacement parts bought at a premium precisely because a line has stopped — and the certificate says nothing about any of it.

How old the drivers are and how long they have held a wheel matters more here than in most states, because the regulation opens the seat at eighteen and an underwriter does not have to follow. And beneath all of it sits the customer paperwork: demands that the policy name the shipper as an insured, respond first and without contribution, and give up its rights of recovery. Signing those changes the program while leaving every physical fact about the operation untouched.

  • Own property certificate or leased to an authorized carrier, and what is running off-dispatch.
  • Per-vehicle license count under KRS 281.631, since the vehicle credential precedes the company one.
  • Registered weight, actual gross weight and both unit ratings, against the eighteen-thousand-pound break the statute does not define.
  • Radius as a distribution, and how often a load crosses one of Kentucky’s seven state lines.
  • Commodity mix and the value of the heaviest single load, in a state that sets no property cargo figure.
  • Driver ages, given the intrastate eighteen-year-old provision and how underwriters price it separately.
  • Renewal and filing calendars treated as one calendar, because cancellation stops the operating rights immediately.
Where the Commonwealth is silent, and where its own forms are

Read Chapter 281 and 601 KAR 1:005 end to end and the trade is simply not present under any of its working names. The Commonwealth has defined nothing, has not made it a fourteenth certificate class, has drawn no table around it and requires no endorsement written for it. Two general things catch it instead: hauling for money, and a safety definition imported from elsewhere without a word changed.

There is also a place where the state’s own paperwork does not match its statute, and it is worth knowing about before an application. 601 KAR 1:040 Section 1 is captioned “Kentucky Intrastate Passenger or Household Goods Authority” and lists no property application form. The property certificate lives in the statute at KRS 281.630 and is not served by a form in that regulation. An applicant working from the regulation alone would not find the credential the statute requires.

And there is a question this page leaves open rather than closing. The eighteen-thousand-pound rung in the liability table is stated in terms — “Gross Weight”, “on each vehicle” — that do not settle how a truck and a loaded gooseneck are measured together, and nothing in KRS 281.010 supplies the missing definition. That is not an access problem. Every relevant section was read; the statute simply does not say.

Which leaves the shape of the state as a single sentence. Kentucky’s safety rules start where the federal definition starts, its certificate and its filed policy start at the first paid pound, the gap between them is ten thousand pounds, and the only weight figure in the safety regulation governs an identification duty for farm vehicles and nothing else.

Coverage lines a Kentucky hot shot account usually carries

The state minimum is a licensing threshold. The program an operator actually needs is built from these lines:

  • Trucking Auto Liability — Primary liability coverage for bodily injury and property damage caused by your truck while under dispatch.
  • Physical Damage — Collision and comprehensive coverage for the tractor, trailer, and attached equipment you own or finance.
  • Motor Truck Cargo — Coverage for the freight you haul against loss or damage in transit.
  • Trailer Interchange — Coverage for non-owned trailers you pull under written interchange agreements.
  • General Liability — Coverage for premises and operations liability away from the truck — terminal yards, customer docks, and non-driving exposures.
  • Workers Compensation — Statutory coverage for driver and yard-employee injury, structured for trucking payrolls and interstate operations.
  • Non-Trucking (Bobtail) Auto Liability — Liability coverage for the tractor when operated off-dispatch — bobtailing home or running personal errands.
  • Pollution Liability — Coverage for cargo-related pollution events and upset/overturn spills not covered by standard auto liability.

Why Truck Guard Insurance for a Kentucky hot shot account

We write hot shot and expedited hauling as a named class rather than as an exception to general trucking, and we read each account against the weight and authority regime of the state it operates in. For a Kentucky operator that means starting from the rating of the power unit and the trailer separately rather than from the combination, sizing cargo against the heaviest load actually carried rather than the average one, and treating the state line as a rating fact because a single crossing can change which driver file the operation owes.

If the operation also runs freight under separate authority, the Kentucky trucking insurance page covers the state’s broader motor carrier picture, and the hot shot trucking insurance page covers the class mechanics that apply wherever the operator runs.

Kentucky hot shot trucking insurance questions

Is there a weight below which Kentucky does not require a motor carrier certificate?

No. KRS 281.630(1) provides that a person shall not act as a motor carrier without first obtaining a certificate from the department, and the definition at KRS 281.010(34) turns on what the person does rather than on the vehicle. All sixteen subsections of KRS 281.605 were read and none is weight-based; its private-carriage exemption is expressly limited to business “other than the business of transportation of property for hire.” The section’s lead-in also carries the words “except as to safety regulations”, so an exemption from the economic chapter is not an exemption from the safety regime.

Which rung of the Kentucky liability table applies to a truck pulling a loaded gooseneck?

That is genuinely unresolved and this page will not guess. KRS 281.655(4) sets $100,000 / $300,000 / $50,000 at “18,000 lbs. or less” and $100,000 / $600,000 / $50,000 at “More than 18,000 lbs.”, with the table headed “Gross Weight” and the lead-in reading “on each vehicle”. Neither phrase says combined, and no definition resolving gross vehicle weight rating against gross combination weight rating against registered weight was located in KRS 281.010. The break changes the amount, not the existence of the duty.

What happens in Kentucky if the filed policy is canceled?

The operating rights stop. KRS 281.655(9) provides that upon cancellation of any bond or policy required by the section, “all operating rights granted by the certificate for which the bond or policy was filed, shall immediately cease”, and the department may require the immediate cessation of operations and the surrender of all certificates and licenses. KRS 281.655(8) requires thirty days’ notice to the department before an insurer is relieved of liability, with earlier cancellation permitted only where a substitute is already in force.

Does Kentucky require a cargo insurance filing for general freight?

No. KRS 281.655(7) requires cargo protection only before a household goods certificate is issued or renewed, in the amounts required by 49 C.F.R. § 387.303(c), with the Kentucky cargo policy endorsement attached. The whole of KRS 281.655 was read, through subsection (13), and cargo appears nowhere else in it. The two administrative regulations that once carried insurance detail — 601 KAR 1:100 and 601 KAR 1:101 — are both repealed, so the statute is the only live source.

Can an eighteen-year-old drive an intrastate load in Kentucky?

Under the safety regulation, yes, with conditions. 601 KAR 1:005 Section 4(2) provides that except for a transporter of hazardous materials subject to 601 KAR 1:025, an operator driving in intrastate commerce is not required to be twenty-one under 49 C.F.R. § 391.11(b)(1) but shall be at least eighteen. A hazardous-materials movement takes it away, and no insurer is obliged to follow the regulation: a young driver is rated on claims history, not on what the Commonwealth permits.

Does the 26,000 pound figure in the Kentucky safety regulation set a threshold for freight?

No, and it is the easiest figure in Kentucky law to misread. It appears only at 601 KAR 1:005 Section 4(4), as an exception to the intrastate USDOT number requirement “for a farm-to-market agricultural transportation motor vehicle with a gross vehicle weight rating of 26,000 pounds or less.” It governs who is excused from applying for and displaying the identification number, for farm-to-market vehicles. It is not a safety trigger and not an economic one.

How does a Kentucky property certificate compare on cost with the other classes?

It is the outlier. KRS 281.630(3)(b) sets an application fee of $250 for all applications, except $25 for a property certificate, out of thirteen enumerated certificate types. The certificate is not the whole credential, though: KRS 281.630(3)(c)2. requires a motor carrier vehicle license application for each motor carrier vehicle under KRS 281.631, and at least one such application must be filed before the applicant is eligible for a certificate.

How much does hot shot insurance cost in Kentucky?

Premium is not published and an estimate made at a distance would be invented. It turns on whether the property certificate is held directly or the trucks are leased to an authorized carrier; on how many vehicles carry their own license under KRS 281.631; on the registered and actual weights, measured against a statutory break the statute never defines; on where the freight actually went last quarter across seven bordering states; on what a full deck of the commodity being hauled is worth, in a state that names no property cargo figure; on the ages of the drivers; and on what the customer paperwork demands of the policy.

Sources

Every figure on this page was read at the source below on August 31, 2026, with the effective date of the version read. Treat each as current as of that date rather than as permanent.

  • KRS 281.630 — Certificates issued by department; applications; fees; renewal — Subsection (1), the prohibition on acting as a motor carrier without a certificate, with no weight element; (2), the intrastate property certificate; (3)(a), the thirteen enumerated certificate types; (3)(b), the $250 application fee with the $25 exception for a property certificate; (3)(c)2., the motor carrier vehicle license application required for each vehicle under KRS 281.631 with at least one required before eligibility; and (3)(c)5., the filing of approved bonds or policies as required by KRS 281.655. Read August 31, 2026, from the Legislative Research Commission’s own statute service..
  • KRS 281.655 — Bonds or insurance policies — Subsection (1), the continuous filed policy or bond with the state insurance endorsement attached; (3), blanket coverage for all equipment operated pursuant to the certificate or permit; (4), the property table with rungs at “18,000 lbs. or less” and “More than 18,000 lbs.”, headed “Gross Weight” and introduced “on each vehicle”; (7), the household-goods-only cargo duty with the Kentucky cargo policy endorsement; (8), the thirty-day insurer cancellation notice; (9), the immediate cessation of operating rights on cancellation. Section read in full to subsection (13). Effective July 15, 2024; amended 2024 Ky. Acts ch. 176, sec. 15. Read August 31, 2026. ⚠ The research packet recorded this section as eight subsections; it runs to thirteen..
  • KRS 281.605 — Exemption of motor vehicles used for certain purposes — The lead-in carried verbatim — “The provisions of this chapter shall not apply, except as to safety regulations, to:” — and all sixteen subsections, read in full as the denominator for the negative that no weight-based exemption exists for general-freight property carriage. Subsection (5), the private-carriage exemption expressly limited to business other than the transportation of property for hire. Read August 31, 2026..
  • KRS 281.010 — Definitions for chapter — Subsection (34), the definition of motor carrier, which carries no weight element and expressly excepts persons leasing to authorized motor carriers. Read August 31, 2026 as the source of the negative that no definition in the chapter resolves gross vehicle weight rating against gross combination weight rating against registered weight for the § 281.655(4) table..
  • 601 KAR 1:005 — Motor carrier safety administrative regulation — Section 2, importing the 49 C.F.R. 390.5 definitions unaltered for for-hire and private carriage, interstate or intrastate, and listing the adopted parts; Section 4(2), the eighteen-year-old intrastate provision with its hazardous-materials exception; Section 4(4), the intrastate USDOT number and “KY” display requirement, whose only weight figure is the farm-to-market exception at 26,000 pounds or less; and the regulation’s own necessity statement recording that Kentucky is more stringent than 49 C.F.R. 391.68(c) and does not allow those medical waivers. Read August 31, 2026..

Get a Kentucky hot shot trucking insurance quote

Send the power unit and trailer ratings separately, the radius distribution, and whether any dispatch crosses a state line. We will size the program against the work the trucks actually do rather than against a statutory floor.

Start a quote Call 317-942-0549