Motor carrier classes by state

New York hot shot trucking insurance for light-combination and expedited freight operators

New York does something to the weight test that most states do not: it reads the scale as well as the sticker. The definition reaches a vehicle at a gross vehicle weight rating or gross combination weight rating, or a gross vehicle weight or gross combination weight, of 4,537 kg — 10,001 lbs — or more, whichever is greater. A truck that rates under the line and loads over it is inside anyway. And the safety chapter that says so contains no insurance provision at all; the money sits in a different article with its own numbers and its own forms.

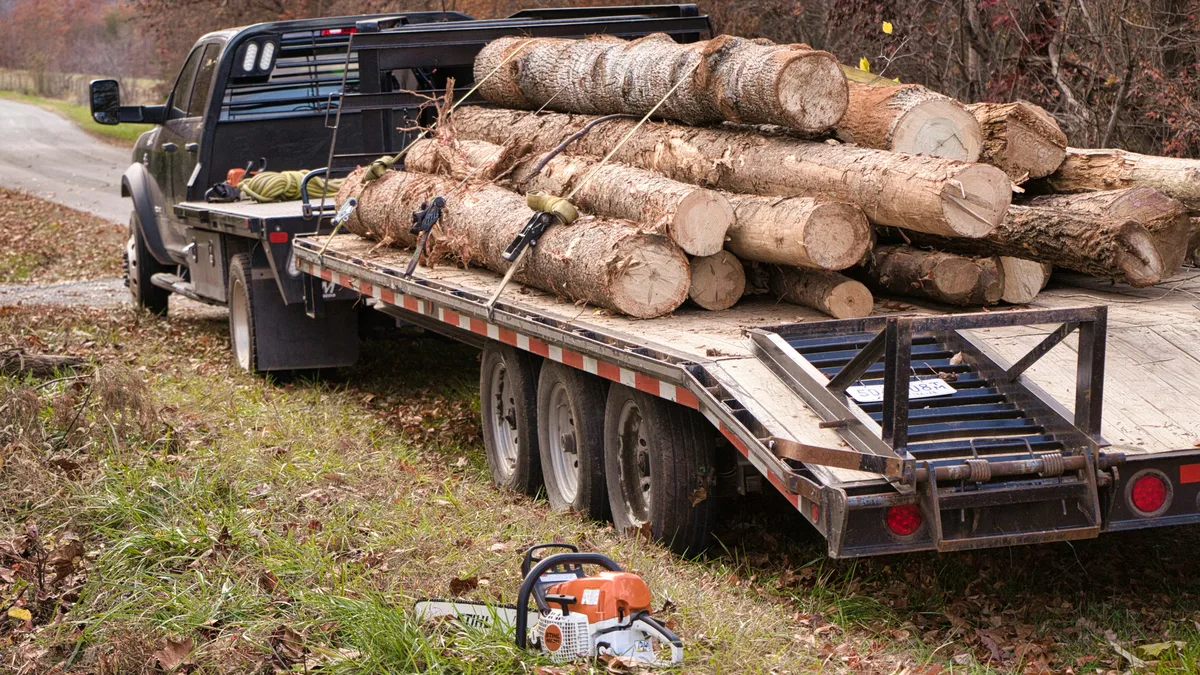
Flatbed dually towing a gooseneck flatbed trailer loaded with logs — New York Hot Shot Trucking Insurance from Truck Guard Insurance

Everything about light-combination hauling that behaves the same in New York as in Nevada — the securement duty that resets with each load, the delivery window with no slack in it, the way one shipment can be worth more than a cargo limit written against an average one — is a property of the equipment and the trade rather than of any state. The hot shot trucking insurance page carries all of it, and nothing below duplicates that.

New York’s own contribution comes in three parts that have to be read together. The safety chapter writes a definition that tests actual weight alongside rating, and reaches intrastate operations by an unusual drafting route — it does not rewrite the word interstate, it redefines the word commerce. That chapter then freezes the federal text it adopts at a specific edition, and the edition is more than a decade old. And it contains nothing at all about insurance, because the filing regime is a separate article in the same title with its own dollar figures, its own exceptions, and a full catalog of uniform forms.

The exceptions in that filing article are the most carefully drafted thing on this page. One of them is written on a rationale rather than as a list — it exempts trucks used exclusively in carrying commodities “that would not be injured by an accident to the truck”, which is a description of a category rather than an enumeration of it. Another exempts contract carriers from the cargo half of a duty that the same article imposes on common and contract carriers alike. Both are quoted below in full.

One thing this page marks as unestablished rather than guessing at. The filing duty is scoped to carriers “under the jurisdiction of the commissioner”, and the instrument that defines that jurisdiction was not read for this page. The section on that says exactly what it leaves open.

Running a truck and trailer inside New York that rates under 10,001 pounds but loads over it? New York’s definition takes the greater of rating and actual weight, so the load can put the vehicle inside the rule on a day the paperwork says it is outside.

Send the rating and a realistic loaded weight separately, and tell us whether you would describe the operation as a common carrier or a contract carrier. In New York that second answer decides whether a cargo filing is owed.

Start a New York quote

New York weighs the truck as well as rating it

The definition that governs is in the New York State Department of Transportation’s motor carrier safety chapter, and it is the state’s own text rather than an unaltered import. 17 NYCRR 820.1(c) provides that wherever the adopted federal provisions refer to a commercial motor vehicle, the reference “shall mean any self-propelled or towed motor vehicle used on a highway in commerce to transport passengers or property when the vehicle: (1) has a gross vehicle weight rating or gross combination weight rating, or gross vehicle weight or gross combination weight of 4,537 kg (10,001 lbs.) or more, whichever is greater”, together with three further prongs covering vehicles built or used to carry more than eight people for hire, more than fifteen people not for hire, and hazardous materials in placardable quantity.

Four measures in one clause, and the operative words are the last two. Rating or actual weight. Vehicle or combination. Whichever is greater. New York does not accept a manufacturer’s figure as the end of the inquiry when the vehicle is heavier than its figure.

That matters more on this equipment than on almost any other, because light combinations are where rating and reality most often diverge. A rating is a fixed number on a label. A gross combination weight is what the truck and the trailer and the freight actually add up to on the day. An operator who has assured themselves that the rating sits under the line has answered one of the four measures.

The practical consequence is a threshold that can be crossed by loading rather than by buying. Nothing about the vehicle changes. A heavier consignment goes on the same trailer behind the same truck, and the whichever-is-greater clause reaches the higher number. There is no transition period written into the definition and nothing announces the crossing.

It is worth being exact that none of this was drafted with this line of work in mind. No New York statute or rule read for this page names it. The state wrote a definition to close a gap between rated and actual weight, for reasons of its own, and this equipment happens to be where that gap is widest.

  • Gross vehicle weight rating — the manufacturer’s figure for the power unit.
  • Gross combination weight rating — the manufacturer’s figure for the pairing.
  • Gross vehicle weight — what the power unit actually weighs.
  • Gross combination weight — what the whole thing actually weighs, loaded.
  • The rule takes whichever of the four is greater, so the load can decide the answer even when every rating sits below the line.

Reaching intrastate operations by redefining commerce

The mechanism by which any of this touches an operation that never leaves New York is worth a section of its own, because the drafting route New York chose is not the common one and it changes what a reader should look for.

The usual technique is to take the federal word interstate and instruct that it be read as meaning both interstate and intrastate wherever it appears. Several states do exactly that, and a reader who knows the technique goes looking for a substitution clause.

New York does not have one. Instead, 17 NYCRR 820.1(b) redefines the underlying term: “Commerce. The term commerce shall mean trade, traffic, commerce or transportation within the jurisdiction of New York State which affects trade, traffic, commerce or transportation within the State.” Everything in the adopted federal text that operates on commerce then operates on that definition, which is internal to New York by construction.

The applicability section sets the outer bound. Section 820.0 provides that, in addition to the applicable requirements of the Vehicle and Traffic Law and the Department of Motor Vehicles regulations, the chapter’s definitions, rules and regulations “are applicable to motor carriers and drivers operating in this State pursuant to or requiring registration or operating authority for the transportation of passengers or property including hazardous materials for the United States Department of Transportation or the commissioner and other motor vehicles operated for the commercial transportation of passengers or property”.

Two things in that sentence are worth carrying forward. It reaches carriers operating pursuant to or requiring registration or operating authority — which implies a New York operating authority regime whose defining instrument this page did not read, and the section on unestablished scope returns to that. And its final clause reaches other motor vehicles operated for the commercial transportation of passengers or property, which is a broad residual category rather than a narrow one.

The safety chapter was frozen at a Code of Federal Regulations printed in 2013

The chapter does not follow federal law forward. It incorporates a specific printing, names it, and stops there — and the printing is now more than a decade old.

The incorporation section provides that the provisions of the Code of Federal Regulations incorporated by reference in the Part have been filed in the Office of the Secretary of State of New York, “the publication so filed being the booklets entitled: Title 49 Code of Federal Regulations Parts 100 to 185, Parts 186 to 199 and Parts 200 to 299 and Parts 300 to 399, revised as of October 1, 2013, published by the Office of the Federal Register, National Archives and Records Administration, as a special edition of the Federal Register.”

That is a static incorporation, not a rolling one. A federal amendment made after that date does not reach an intrastate New York carrier through this chapter on its own force; New York would have to re-file. There is nothing in the section that follows federal law forward.

The gap this opens is unusually wide simply because of elapsed time. Federal motor carrier safety law has moved substantially since that printing, and an operator complying with current federal text is complying with something the chapter does not, by its own terms, incorporate. Reasoning about which text governs a given intrastate question in New York is a legal exercise rather than a compliance-checklist one, and the honest position for a page like this is to name the freeze and its date and let the reader take it to counsel.

One transcription detail is worth preserving because a reader checking the source should find it. The section is captioned in the filed document with a bracketed renumbering artifact — the number appears with a struck earlier number beside it — which is present in the text as filed and is not an error introduced here. The document itself opens by repealing the previous sections of the Part and adding new ones, so the whole chapter is a replacement rather than an amendment.

Send the rating and a realistic loaded weight as two separate numbers, your common or contract classification, and the value of the heaviest single load you carry. In New York those three answers settle which rules apply and which filings are owed before any coverage question is reached.

Get a New York quote

Three intrastate exemptions from the hours rule, and none of them is this work

New York writes intrastate exemptions from the federal hours-of-service part that have no federal counterpart, and it is worth knowing precisely who they reach, because the list is short and specific.

The chapter adopts the federal hours part twice over, once for interstate and foreign commerce and once for intrastate commerce, and it is the intrastate adoption that carries the carve-outs. 17 NYCRR 820.6(b) adopts the part for intrastate commerce “except that the provisions of this section shall not apply to: (1) the operation of a commercial motor vehicle owned by a farmer and operated by himself or an employee when used in the hauling of farm, dairy, or horticultural products and farm supplies for himself or his farm neighbors to market; (2) the operation of tow trucks while responding to requests to provide roadside service or to remove wrecked, disabled, abandoned or illegally parked motor vehicles; or (3) nor shall the hours of service accrue to a driver of a utility service vehicle.”

A farmer hauling their own or a neighbor’s produce. A tow truck on a service call. A utility service vehicle. The third of those comes with its own three-part definition in the same subsection, covering vehicles used in repairing, maintaining or operating the physical facilities necessary to deliver electric, gas or steam service, water, sanitary sewer, telephone and cable service; engaged in activity necessarily related to that delivery, including travel between activity sites; and operated primarily within the utility’s service area, without regard to whether the vehicle is owned, leased or rented by the utility.

General-freight light-combination work is none of the three, and the point of setting them out is to be positive about that rather than leaving it as an absence. New York wrote intrastate hours relief. It wrote it for farmers, tow operators and utility crews. An operator on this equipment gets the adopted federal hours part as written.

The last clause of the utility definition is worth noticing for what it shows about how carefully this was drawn. Ownership is expressly irrelevant — a rented vehicle doing utility work qualifies, and a utility-owned vehicle doing something else does not. That is a rule about function, and it is the kind of drafting that indicates the exemptions were meant to be narrow rather than convenient.

The money lives in a different article with different numbers

The safety chapter contains no insurance provision at all. Read in the filed document served by the Department, it returns no occurrence of the word insurance, no occurrence of the phrase financial responsibility, and no reference to the federal financial-responsibility part. That is a complete absence rather than a partial one, and it means an operator who reads only the safety chapter has learned nothing about what New York requires financially.

The requirements are in a separate article of the same title, headed Insurance and sitting inside the motor carriers subchapter. 17 NYCRR 855.1 opens with a chapeau that sets both the class bound and the mechanism: “Every common and contract motor carrier of property under the jurisdiction of the commissioner transporting property for compensation shall secure and maintain and file with the commissioner a surety bond or certificate of a company authorized to do business in this State by the Superintendent of Insurance, or in lieu thereof, may file qualifications as a self-insurer, covering each motor vehicle so to be operated for the sum hereinafter set forth, conditioned for the payment of all judgments recovered against such motor carrier”.

The sums that follow are New York’s own. For personal injury or death of one person, $100,000. For personal injury or death of all persons in one accident, $300,000, with a maximum of $100,000 for each person. For property damage, expressly excluding cargo insurance, $50,000. For loss or damage to property being transported, each motor vehicle, $5,000. And for cargo, aggregate losses or damages at any one time and place, $10,000.

Two structural points about that set. It is per motor vehicle — the chapeau says covering each motor vehicle so to be operated — and it carries an aggregate on the cargo side that the liability side does not have. A single incident that damages freight on more than one vehicle at one time and place is capped at the aggregate figure, and that is a different unit of account from anything in the liability rungs.

The third point is the one with the most practical bite: none of these figures scales with the truck. There is no weight ladder in the article. A light combination and a tractor-trailer running general freight inside New York are on the same state figures, and the article contains no provision that distinguishes them.

  • $100,000 — personal injury or death of one person.
  • $300,000 — personal injury or death of all persons in any one accident, with a maximum of $100,000 for each person.
  • $50,000 — property damage, expressly excluding cargo insurance.
  • $5,000 — loss or damage to property being transported, per motor vehicle.
  • $10,000 — cargo, aggregate losses or damages at any one time and place.
  • No weight ladder anywhere in the article: the figures do not scale with the equipment.
An exception written on a rationale rather than a list

The exceptions to the cargo half of that duty are in one short section, and the first of them is drafted in a way that repays attention because it explains its own logic rather than simply enumerating outcomes.

17 NYCRR 855.3 provides in full: “The provisions and requirements of this Part relative to the maintenance and filing of cargo insurance shall not apply: (a) to trucks used exclusively in the transportation of crushed stone, sand, gravel, mortar, dirt, debris, coal, logs and similar commodities that would not be injured by an accident to the truck; (b) to contract carriers; (c) to certificated bus operators authorized to transport packages for compensation as auxiliary to passenger service.”

Read subdivision (a) closely. It lists eight commodities and then supplies the principle behind them: “and similar commodities that would not be injured by an accident to the truck.” The list is illustrative of a category, and the category is defined by a property of the freight rather than by its name. Crushed stone in an overturned truck is still crushed stone.

That is a rationale a light-combination operator will almost never satisfy, and the reason is definitional. This equipment exists to move things quickly because they are needed quickly, and the things that fit that description are finished goods, components, instruments and assemblies — precisely the class of freight that is destroyed rather than merely spilled when the truck goes over. The exception describes the opposite of this work.

Subdivision (b) is the one that most often decides the answer in practice, and it sits in tension with the section it excepts. The chapeau of 855.1 imposes the duty on “Every common and contract motor carrier of property”. Subdivision 855.3(b) then exempts contract carriers from the cargo requirement specifically. Read together: a contract carrier owes the liability filing and not the cargo filing; a common carrier owes both. The classification is doing real work here, and it is a classification question rather than an equipment question.

Form E and Form H, and what has to happen before a policy can be filed

New York runs the full uniform form catalog and sets out the mechanics in one section, 17 NYCRR 855.4, which is worth reading before setting an operation up rather than discovering piecemeal afterwards.

The certificates are Form E for bodily injury and property damage liability and Form H for cargo. Each has an endorsement that travels with it — Form F and Form I respectively — attached to the original policy. Each has a surety bond alternative, Form G and Form J. Cancellation of either runs on Form K or Form L. There is a separate Form 10 for broker surety bonds.

Two provisions in that section govern how the filings behave over time, and both are traps for an operator changing insurers. Surety bonds and certificates of insurance must specify that coverage will remain in effect continuously until terminated. And cancellation is not effective unless at least thirty days’ written notice of intention to cancel has been delivered to the commissioner. A policy can be canceled between an operator and an insurer long before the filing behind it is canceled with the Department, and the thirty-day clock runs from delivery of notice rather than from the policy date.

Replacement has its own choreography. A replacement bond or certificate requires the commissioner’s acceptance, an authorization letter, and effective dates aligned within a defined window. An operator who assumes a new filing simply supersedes an old one has skipped the acceptance step, and acceptance is what makes the substitution effective.

One further provision constrains who may file at all: no bond or certificate of insurance is to be filed with the commissioner unless a direct contractual relationship exists between the certificate or permit holder and the insurance or bonding company. That excludes filings routed through intermediaries who are not party to the contract, and it means the entity named on the authority and the entity named on the policy have to be the same. The commissioner also retains authority to refuse a bond or certificate found inadequate at any time.

Where the filing duty’s scope runs out, and what this page does not establish

The class bound on the filing duty is a phrase rather than a number, and the phrase points somewhere this page did not go. That is worth stating precisely, because it is the difference between a bounded claim and an overreaching one.

The duty in 855.1 runs to “Every common and contract motor carrier of property under the jurisdiction of the commissioner transporting property for compensation”. There is no weight term in it. On its face the trigger is being a common or contract motor carrier of property, being within the commissioner’s jurisdiction, and carrying property for compensation — three status conditions and nothing dimensional.

If that were the whole story, the answer would be that New York’s money obligation attaches at any weight, which would be a strong and interesting result. But the middle condition is a scope term, and the instrument that defines the commissioner’s jurisdiction over property carriers sits in the Transportation Law rather than in these regulations, and was not read for this page.

So the honest statement is bounded: the filing duty in Part 855 carries no weight qualifier on its face, and whether a particular for-hire intrastate operation is within the commissioner’s jurisdiction is answered by a statute this page did not open. An operator should not conclude from this page either that they are inside the duty or that they are outside it. They should conclude that the regulation does not decide it by weight, and that the question is worth putting to the Department directly.

What is established, and worth separating from what is not: Part 855 has four sections, and all four were read in full — the section setting the sums, the section incorporating federal levels for interstate carriers of property as housekeeping, the exceptions section, and the general requirements section with the form catalog. Probing beyond section four returned a generic index document rather than further sections, so the article is complete at four and the reading of it is complete.

Similarly bounded: nothing on this page claims a New York variant of the federal short-haul air-mile provisions, in either direction. The safety chapter as filed returns no occurrence of the phrase, and the hours part is adopted subject only to the three intrastate exemptions set out above.

Two weights, one classification, and the rest of the file

Premium on this equipment is not tabled anywhere and cannot be reverse-engineered from anything above, since every dollar figure on this page is a regulatory floor rather than a measure of exposure. What follows is the evidence that gets read, in the order New York makes it matter.

In New York the first input is the pair of weights rather than one weight, and the reason is the whichever-is-greater clause. The rating of the power unit, the rating of the combination, and a realistic loaded weight are three different numbers, and the state’s definition takes the largest. An operator who reports only the rating has reported the number least likely to be the operative one, and an underwriter who prices on it is pricing a different vehicle from the one that is being driven.

Carrier classification is second and it is unusually consequential here. Common carrier or contract carrier decides whether the cargo filing is owed, because the exceptions section exempts contract carriers from the cargo half of the duty. It also correlates with what underwriters read directly: dedicated lanes under continuing agreements produce a different loss profile from load-board work with a changing customer set.

Commodity is third, and in New York it carries a specific regulatory edge as well as the usual rating one. The cargo exception is drawn on whether the freight would be injured by an accident to the truck, so the character of the freight decides whether the exception could ever be in play — and for this work it essentially never is. Separately, the value of the heaviest load carried is what the motor truck cargo limit should be set against, because the state figures are filing thresholds and the aggregate figure is lower still.

Radius is fourth, expressed as a distribution rather than a maximum, and in New York it has an unusual geography to it. The state runs several hundred miles east to west with dense freight demand at both ends, and it borders five states plus Canada. An operation that is genuinely intrastate in the Hudson Valley looks nothing like one in the western counties, and the frequency of crossings is what gets priced rather than the theoretical maximum.

Two layers close the file. Whose authority the truck moves under — the operator’s own, or a lease to somebody larger — settles which policy responds and how much of the exposure falls to non-trucking and bobtail liability once the trailer is off. The customer paperwork supplies the remainder — the shipper written in as an insured, a covenant that this policy answers before any other, recovery rights given up in advance, and physical damage liability accepted for equipment the operator has borrowed. Driver ages and time in the seat sit outside all of it, read straight off loss experience.

  • Two numbers, not one: the rating, and what the outfit actually scales loaded. The definition takes the larger.
  • The common-or-contract classification, which alone settles whether a cargo filing exists.
  • What is hauled — relevant both to the rationale behind the cargo exception and to sizing a limit off the largest shipment.
  • The spread of actual runs across a state that touches five others and an international border.
  • Are Form E and Form H live, and does the name on the authority match the name on the policy?
  • Whose authority the truck moves under — the operator’s own, or a lease to somebody larger.
  • The customer paperwork: the shipper written in as an insured, answers-before-any-other wording, recovery rights given up, borrowed-trailer damage.

Absences that carry as much as the text does

Three things go unsaid here, and the second of them is a full-text result rather than an impression, which is why it is worth stating as one.

The trade has no name in New York law. Nothing defines it, no permit category is addressed to it, no schedule is written against it, no endorsement is demanded of it. What catches it is a definition drafted to close a gap between rated and scaled weight, and an article addressed to carriers of property at large.

On insurance the safety chapter is completely silent — and that is measured, not impressionistic: the filed document returns not one occurrence of the word. Somebody could read that chapter end to end, carefully, and come away knowing nothing whatever about New York’s financial requirements, with no line in it hinting that a second document exists.

The two also decline to acknowledge one another, despite sharing a title. One is keyed to a federal printing from 2013 and to commercial motor vehicles as it defines them; the other is keyed to the commissioner’s jurisdiction over common and contract carriers of property and contains no weight whatever. Nothing anywhere warns that falling outside one leaves you inside the other. Reading both is the only route to that.

So no lookup gets an operator there. The position has to be built out of a four-measure definition, a redefined noun, an incorporation date more than a decade stale, a set of figures sitting in a different article, and an exception whose test is whether the freight survives a rollover. Five provisions, drafted apart, pointing nowhere near each other.

Coverage lines a New York hot shot account usually carries

The state minimum is a licensing threshold. The program an operator actually needs is built from these lines:

  • Trucking Auto Liability — Primary liability coverage for bodily injury and property damage caused by your truck while under dispatch.
  • Physical Damage — Collision and comprehensive coverage for the tractor, trailer, and attached equipment you own or finance.
  • Motor Truck Cargo — Coverage for the freight you haul against loss or damage in transit.
  • Trailer Interchange — Coverage for non-owned trailers you pull under written interchange agreements.
  • General Liability — Coverage for premises and operations liability away from the truck — terminal yards, customer docks, and non-driving exposures.
  • Workers Compensation — Statutory coverage for driver and yard-employee injury, structured for trucking payrolls and interstate operations.
  • Non-Trucking (Bobtail) Auto Liability — Liability coverage for the tractor when operated off-dispatch — bobtailing home or running personal errands.
  • Pollution Liability — Coverage for cargo-related pollution events and upset/overturn spills not covered by standard auto liability.

Why Truck Guard Insurance for a New York hot shot account

We write hot shot and expedited hauling as a named class rather than as an exception to general trucking, and we read each account against the weight and authority regime of the state it operates in. For a New York operator that means starting from the rating of the power unit and the trailer separately rather than from the combination, sizing cargo against the heaviest load actually carried rather than the average one, and treating the state line as a rating fact because a single crossing can change which driver file the operation owes.

If the operation also runs freight under separate authority, the New York trucking insurance page covers the state’s broader motor carrier picture, and the hot shot trucking insurance page covers the class mechanics that apply wherever the operator runs.

New York hot shot trucking insurance questions

How does New York decide whether a truck is a commercial motor vehicle?

By taking the greatest of four measures. 17 NYCRR 820.1(c)(1) reaches a vehicle with “a gross vehicle weight rating or gross combination weight rating, or gross vehicle weight or gross combination weight of 4,537 kg (10,001 lbs.) or more, whichever is greater.” Rating or actual weight, vehicle or combination, whichever is greater. A vehicle that rates under the line and loads over it is inside the definition on that load, and nothing announces the crossing.

How does New York apply the federal safety rules to intrastate operations?

By redefining commerce rather than by rewriting interstate. 17 NYCRR 820.1(b) provides that “The term commerce shall mean trade, traffic, commerce or transportation within the jurisdiction of New York State which affects trade, traffic, commerce or transportation within the State.” Everything in the adopted federal text that operates on commerce then operates on that internal definition. A reader looking for a word-substitution clause will not find one, because New York used a different technique.

Which edition of the federal safety regulations does New York use?

A fixed one, and an old one. The incorporation section of Part 820 names the booklets filed with the Secretary of State as Title 49 Code of Federal Regulations Parts 100 to 185, Parts 186 to 199, Parts 200 to 299 and Parts 300 to 399, “revised as of October 1, 2013”. That is a static incorporation. A federal amendment made after that date does not reach an intrastate New York carrier through this chapter on its own force, and the elapsed time makes the gap a wide one.

What liability limits does New York require of a motor carrier of property?

17 NYCRR 855.1 requires every common and contract motor carrier of property under the commissioner’s jurisdiction, transporting property for compensation, to secure, maintain and file coverage covering each motor vehicle operated: $100,000 for personal injury or death of one person; $300,000 for all persons in any one accident with a maximum of $100,000 each; and $50,000 for property damage, expressly excluding cargo insurance. There is no weight ladder in the article — the figures do not scale with the equipment.
Does New York require a cargo insurance filing?

For common carriers, yes. 17 NYCRR 855.1 sets cargo at $5,000 for each motor vehicle and $10,000 for aggregate losses or damages at any one time and place, filed on Form H with a Form I endorsement attached to the original policy. But 17 NYCRR 855.3(b) exempts contract carriers from the cargo requirement specifically, so a contract carrier files the liability certificate and not the cargo one. The classification decides it, not the equipment.

What is the New York cargo exception for commodities that would not be injured?

17 NYCRR 855.3(a) exempts from the cargo filing “trucks used exclusively in the transportation of crushed stone, sand, gravel, mortar, dirt, debris, coal, logs and similar commodities that would not be injured by an accident to the truck.” The eight commodities are illustrative and the final clause is the actual test. Light-combination freight is generally the opposite case — finished goods, components and assemblies that are destroyed rather than spilled — so the exception is very unlikely to reach this work.

Does New York have intrastate hours-of-service exemptions?

Three, and none reaches general freight. 17 NYCRR 820.6(b) adopts the federal hours part for intrastate commerce except for a commercial motor vehicle owned by a farmer and operated by himself or an employee hauling farm, dairy or horticultural products and farm supplies for himself or his farm neighbors to market; the operation of tow trucks responding to roadside service or removal requests; and drivers of utility service vehicles, defined in the same subsection by function rather than by ownership.

How do the New York insurance filings work in practice?

17 NYCRR 855.4 sets the mechanics. Form E is the liability certificate and Form H the cargo certificate, with Form F and Form I as their endorsements and Form G and Form J as surety bond alternatives; cancellation runs on Form K or Form L. Coverage must specify that it remains in effect continuously until terminated, and cancellation is ineffective unless at least thirty days’ written notice has been delivered to the commissioner. A filing also requires a direct contractual relationship between the certificate or permit holder and the insurer or bonding company.

What does a New York underwriter need before quoting this class?

Both weights as separate numbers — the rating and what the outfit actually scales loaded — because the state definition takes the larger and reporting only the first describes a different vehicle. Then the common-or-contract classification, which alone settles whether a cargo filing exists. Then what is hauled and the value of the largest shipment, since the state figures are floors rather than measurements. Then the spread of actual runs, whose authority the truck moves under, whether Form E and Form H are live, driver ages, and the customer paperwork. No schedule prices this class and a sight-unseen range would be fabricated.

Sources

Every figure on this page was read at the source below on August 31, 2026, with the effective date of the version read. Treat each as current as of that date rather than as permanent.

  • 17 NYCRR Part 820 — Motor Carrier Safety (New York State Department of Transportation, filed text) — Read August 31, 2026 direct from the Department’s own repository: 49,697 bytes, application/pdf, 18 pages, md5 6b436fde9975c9dbf9530d88919c75e4, text extracted with layout preserved. Section 820.0 (Applicability), 820.1(a)–(c) including the four-measure commercial motor vehicle definition and the redefinition of commerce, 820.6(a)–(b) including the three intrastate hours exemptions and the utility service vehicle definition, and the incorporation section naming the federal booklets “revised as of October 1, 2013”. Full-text checks on the served document this date: “387” zero occurrences, “insurance” zero occurrences, “air mile” zero occurrences. The document opens by repealing the prior sections of the Part and adding new ones..
  • 17 NYCRR 855.1 — Common and contract motor carriers — Read August 31, 2026; title block served as “N.Y. Comp. Codes R. & Regs. Tit. 17 § 855.1 - Common and contract motor carriers”. The chapeau imposing the secure, maintain and file duty on every common and contract motor carrier of property under the commissioner’s jurisdiction transporting property for compensation, covering each motor vehicle operated. The sums: $100,000 one person; $300,000 all persons in one accident with a maximum of $100,000 each; $50,000 property damage excluding cargo insurance; $5,000 cargo per motor vehicle; $10,000 cargo aggregate at any one time and place..
  • 17 NYCRR 855.3 — Exceptions — Read August 31, 2026 in full; title block served as “N.Y. Comp. Codes R. & Regs. Tit. 17 § 855.3 - Exceptions”. Three exceptions from the cargo maintenance and filing requirement: trucks used exclusively in carrying eight named commodities “and similar commodities that would not be injured by an accident to the truck”; contract carriers; and certificated bus operators authorized to carry packages auxiliary to passenger service. Note the tension carried forward on the page: 855.1 imposes the duty on common and contract carriers alike, and 855.3(b) then removes contract carriers from the cargo half of it..
  • 17 NYCRR 855.4 — General requirements — Read August 31, 2026; title block served as “N.Y. Comp. Codes R. & Regs. Tit. 17 § 855.4 - General requirements”. The form catalog — Forms E and H as certificates, F and I as endorsements, G and J as surety bonds, K and L for cancellation, and Form 10 for broker surety bonds. Continuous coverage until terminated. Cancellation ineffective without at least thirty days’ written notice delivered to the commissioner. Replacement requiring the commissioner’s acceptance, an authorization letter and aligned effective dates. The requirement of a direct contractual relationship between the certificate or permit holder and the insurer or bonding company, and the commissioner’s retained authority to refuse an inadequate filing..
  • New York Transportation Law — jurisdiction of the commissioner over property carriers — NOT READ — Listed as a named gap rather than as a source. The filing duty in 17 NYCRR 855.1 is scoped to carriers “under the jurisdiction of the commissioner”, and 17 NYCRR 820.0 refers to carriers operating pursuant to or requiring registration or operating authority. The statute defining that jurisdiction and any associated operating-authority regime was not read for this page, so no claim is made about whether a given for-hire intrastate operation falls inside it. What is established is that the regulation itself contains no weight qualifier..

Get a New York hot shot trucking insurance quote

Send the power unit and trailer ratings separately, the radius distribution, and whether any dispatch crosses a state line. We will size the program against the work the trucks actually do rather than against a statutory floor.

Start a quote Call 317-942-0549