
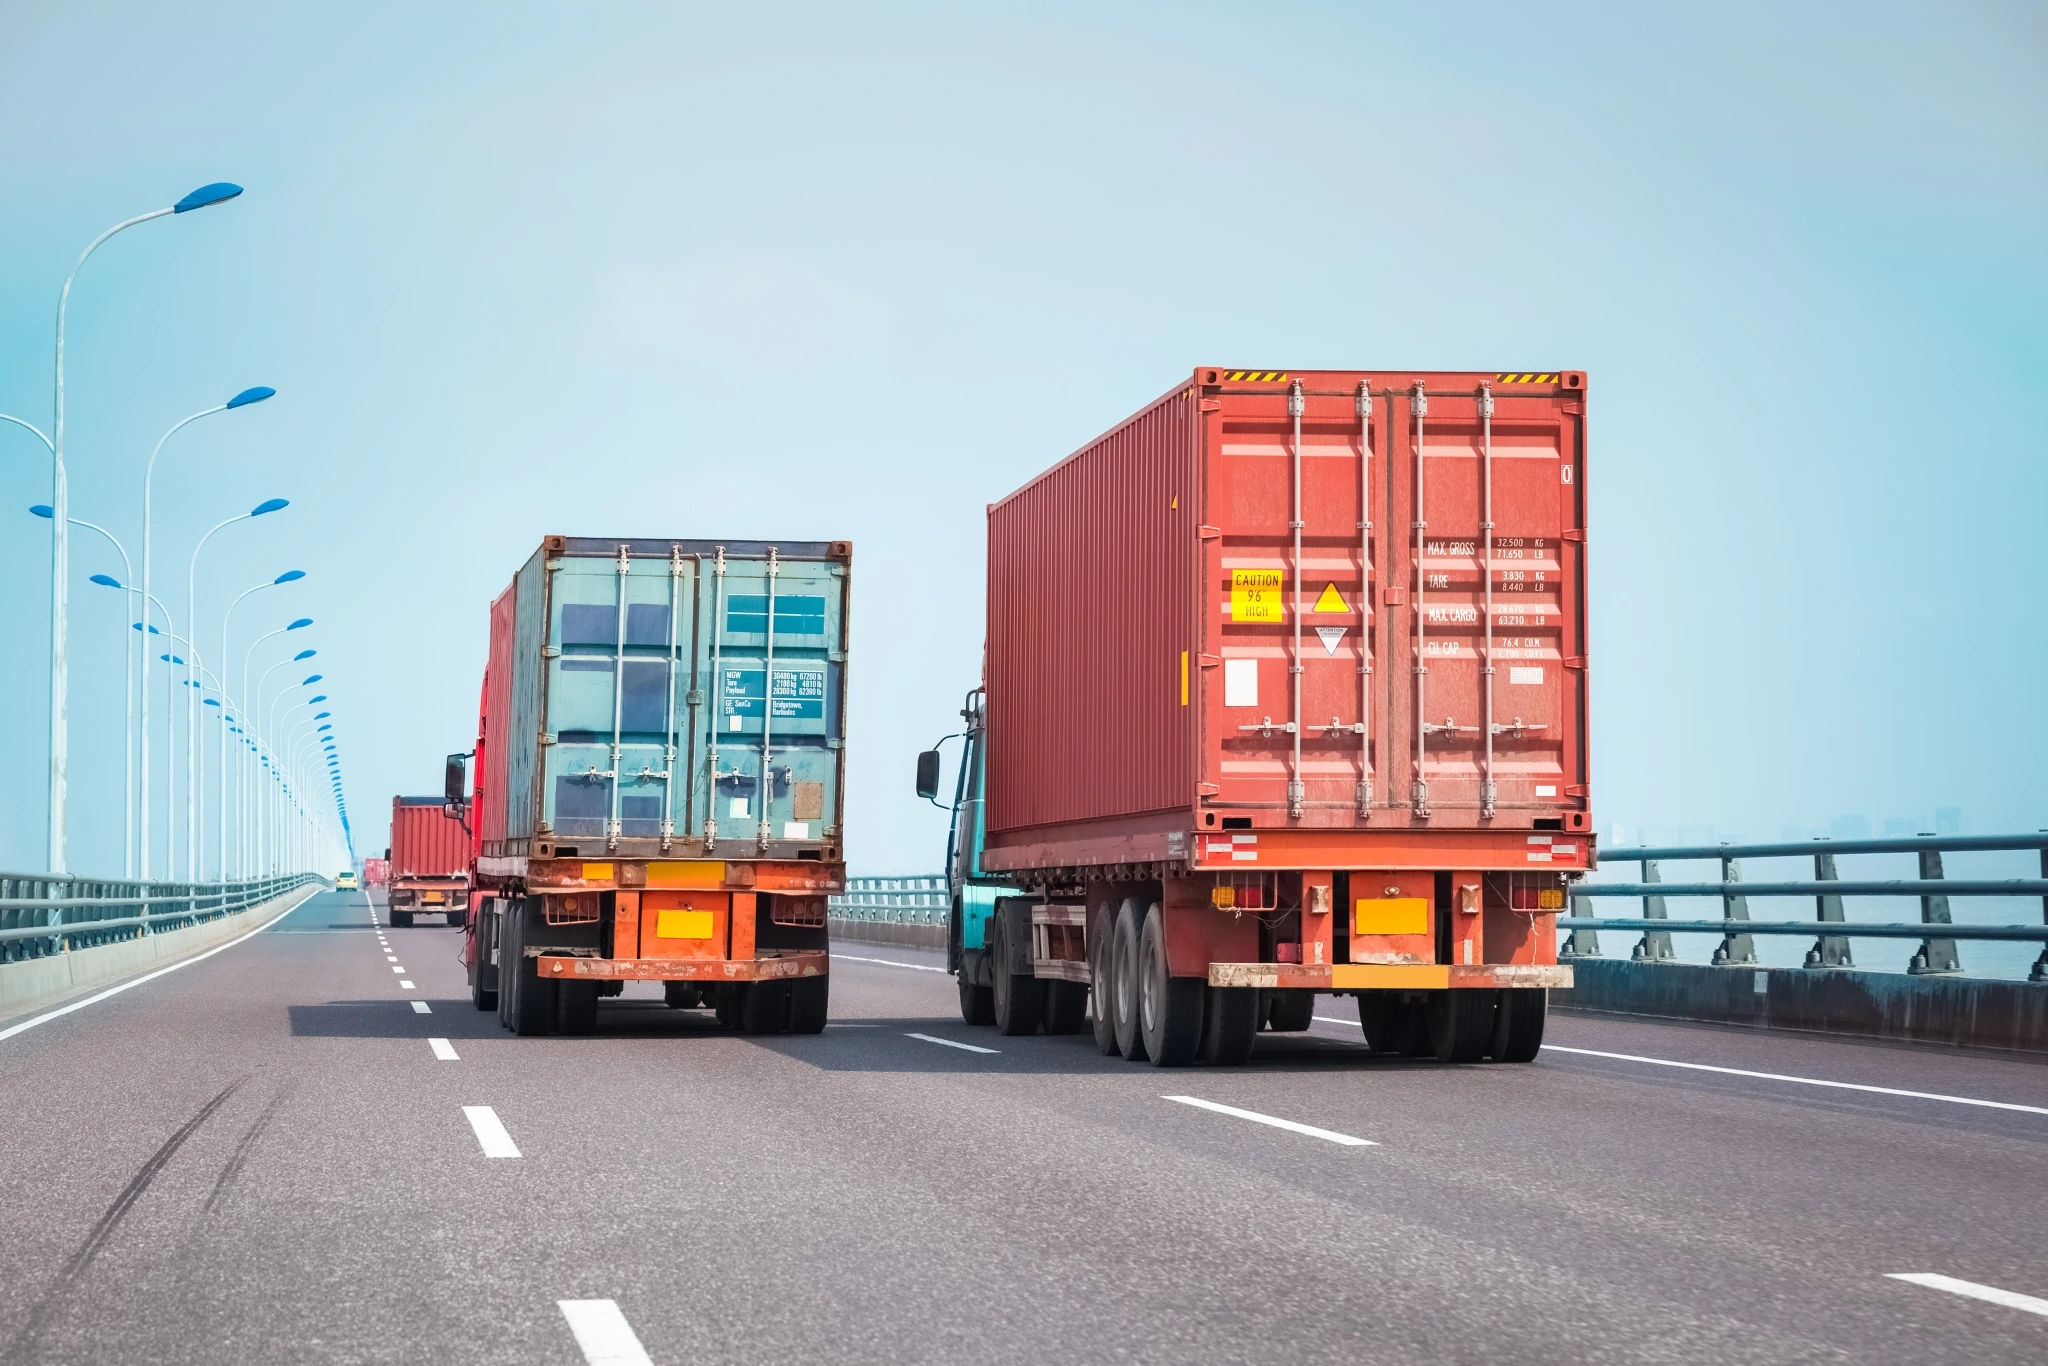

Trailer interchange covers physical damage to the leased or borrowed trailer itself, and motor truck cargo covers the freight inside it. On a trailer you do not own you usually need both, and cargo never stands in for the trailer coverage. Which trailer coverage fits depends on the agreement that put the trailer in your hands.
The question shows up two ways in search: how the two coverages differ, and when a carrier should add interchange instead of relying on cargo. This article answers both.
What is the difference between trailer interchange and motor truck cargo?
They insure different property. Motor truck cargo insures the customer’s freight while it is in your care. Trailer interchange insures a trailer, container or chassis owned by someone else while you hold it under a written interchange agreement. For who is responsible for the chassis and the box, see intermodal trucking insurance for chassis and containers.
They also answer different people. A cargo claim comes from the shipper or the owner of the goods. An interchange claim comes from the owner of the equipment. The two can arise from the same crash, but they are separate claims, made by separate parties, under separate forms.
The broader explanation of interchange, including how the care, custody and control trigger works, is in trailer interchange agreements: when you are liable and what pays. This article stays on the comparison.
Does a leased trailer count as interchange?
It depends on how you hold it. Federal rules on lease and interchange of vehicles treat leasing and interchange as separate arrangements, and insurance forms tend to follow the same split.
A trailer you pick up from a customer’s dock, a rail ramp or another carrier for a single move, under a written interchange agreement, is the classic interchange exposure. A trailer you rent for months from a leasing company is often handled differently: insurers commonly list it on your own physical damage coverage like a trailer you own, with the lessor named as loss payee if the lease asks for it.
Power-only work sits in between. You pull trailers that belong to a shipper or another carrier, often many different ones, under an agreement for each relationship. That usually calls for interchange or a non-owned trailer form rather than scheduling each trailer.
When should a trucking company add trailer interchange instead of relying on cargo?
As soon as it starts pulling trailers it does not own under an agreement that makes it responsible for them. Cargo is never a substitute, because a cargo form does not cover the equipment. A carrier relying on cargo alone for a borrowed trailer has no coverage for the trailer at all.
The trigger is usually one of these:
- Signing an intermodal interchange agreement to haul containers on chassis.
- Taking on a power-only contract.
- Agreeing to swap trailers with a customer or another carrier at a dock or yard.
- Pulling a trailer from a broker’s customer that arrives with its own interchange paperwork.
In each case the agreement typically holds you responsible for the equipment from the moment you take it. Add the coverage before the first trailer, not after the first claim.
Is non-owned trailer coverage an alternative?
For some carriers, yes. Some insurers offer a non-owned trailer physical damage form that covers trailers you use but do not own, with or without a written interchange agreement. It can suit a carrier that pulls a changing mix of trailers under informal arrangements.
Interchange forms are usually written around trailers held under a written agreement, and many equipment providers ask for interchange by name. If your agreements specify interchange, check that a non-owned form will be accepted before you rely on it. Ask your agent which form your insurer writes and which one your providers will take.
Who is liable to the trailer owner after a loss?
The agreement decides first. Most interchange agreements make the carrier responsible for damage to the equipment while it is in the carrier’s possession, with exceptions the agreement spells out. The sample clauses in trailer interchange agreement explained show how that language usually reads.
For the freight, federal law at 49 U.S.C. 14706 makes a carrier that issues a receipt or bill of lading liable for the actual loss or injury to the property. That liability exists whether or not your cargo form covers the cause of loss.
So after a crash with a borrowed trailer, expect two claims: one from the trailer owner under the agreement, and one from the shipper under the bill of lading.
Real-World Scenario: Picture a hypothetical carrier that takes a power-only load for a broker, pulling a shipper’s loaded trailer. A tire failure sends the trailer into a guardrail. The trailer’s side is torn and some of the freight is crushed. The carrier’s cargo form pays for the freight, subject to its terms. The trailer owner sends a repair bill under the interchange agreement the carrier signed at pickup. The carrier had cargo but no interchange or non-owned trailer coverage, so the trailer bill is the carrier’s to pay.
What should you check in a trailer lease or interchange agreement?
Five things. Who owns the trailer. Whether you are responsible for damage while you hold it, and for how long after you drop it. Which coverage the agreement asks you to carry, by name. Whether the owner must be shown on your policy, and how. And how the agreement treats damage that was already there when you picked the trailer up.
That last point matters for claims. Inspect the trailer at pickup and note existing damage on the interchange paperwork, because without that record you may be paying for someone else’s dent. The article on trailer interchange at a drop yard covers the related question of a trailer left at your lot.
What do intermodal agreements ask for on each line?
Intermodal work is the clearest example of an equipment provider asking for both coverages by name. IANA’s UIIA FAQ says individual equipment providers may require insurance beyond the agreement’s base auto and general liability, naming cargo and trailer interchange as examples, and that trailer interchange is a coverage many equipment providers require. Read each provider’s requirements for the form and wording it accepts.
Two practical points follow. First, a narrow interchange form that only covers named perils such as fire and theft may not meet an intermodal requirement, even though it is technically interchange coverage. Second, the type of cargo form matters as much as the limit. Before you sign, compare the wording of both forms against the agreement, not just the numbers on the certificate.
How do the deductibles and claims work differently?
Each policy has its own deductible and its own claim. If one accident damages both the trailer and the freight, you may face two deductibles, two adjusters and two settlements, one with the equipment owner and one with the shipper. Agreements sometimes set how quickly you must report damage to the equipment provider, and cargo forms set their own notice rules.
Report both claims at once, with the same photographs, the interchange receipt and the bill of lading. A carrier that reports the cargo loss and forgets the trailer can find that the equipment owner’s bill arrives after the interchange policy’s notice period has passed.
Which carriers need both coverages?
Most carriers that pull other people’s trailers. Intermodal and drayage carriers, covered by the UIIA intermodal trucking insurance page, need both. So do power-only operations and many dry van carriers in general freight. A carrier that only pulls its own trailers needs cargo and physical damage, and can usually skip interchange.
What should you do next?
List every trailer you pulled last month that you did not own, and the paperwork that came with it. Then start a quote and send the list with your current policies. We will tell you whether cargo, interchange or a non-owned trailer form fits, and where your current program leaves the trailer uncovered.